
Journal · selling
Start here · Azusa short sale
What Is a Short Sale in Azusa, and How Do You Do One?
A short sale is a sale of an Azusa home for less than the mortgage balance, made only with the lender's or servicer's written approval. The usual steps are to talk with the servicer and a HUD-approved counselor, list the home, submit an offer with a hardship package, and close only after written lender approval.
Azusa sellers ask this in many ways. Each question below is answered in this note.
- How do I do a short sale in Azusa?
- What is the Azusa short sale process, step by step?
- Do I qualify for a short sale in Azusa?
- What should go in an Azusa short sale hardship letter?
- How long does a short sale take in Azusa?
- Will my lender approve a short sale in Azusa?
- What is the difference between a short sale and a foreclosure in Azusa?
- What is a deed in lieu of foreclosure on an Azusa house?
- How does a loan modification compare with a short sale in Azusa?
- Can I do an Azusa short sale if I have a second mortgage or HELOC?
- How does a short sale affect credit for an Azusa homeowner?
- Can the lender seek a deficiency after an Azusa short sale under CCP 580e?
- Will I receive a 1099-C after an Azusa short sale?
- Can I live in my Azusa house during a short sale?
- Who pays the realtor in an Azusa short sale?
- Can I short sell an Azusa rental or investment property?
- What happens after a notice of default on an Azusa house?
- What if I am behind on mortgage payments in Azusa?
- What if I am underwater on an Azusa house?
- How do I find an Azusa short sale realtor?
- How do I find an Azusa short sale real estate agent?
- Who is a short sale realtor in Azusa?
- Who is a short sale real estate agent in Azusa?
- How do I find an Azusa short sale listing agent?
- Who is a short sale specialist in Azusa?
- How do I find a realtor specializing in short sales in Azusa?
- How do I hire a short sale realtor in Azusa?
- How do I find the best short sale realtor in Azusa?
- Who handles short sales in Azusa?
- How do I find a distressed property realtor in Azusa?
- How do I find a short sale realtor near me in Azusa?
- What should I look for in an Azusa short sale listing agent?
- What should I ask an Azusa short sale realtor before I list?
- Who can help me if I owe more than my Azusa house is worth?
- How do I find a realtor if I owe more than my Azusa house is worth?
- Who can help me sell a house for less than the mortgage in Azusa?
- How do I find a realtor for an upside-down mortgage in Azusa?
- Who can help me sell an underwater house in Azusa?
- How do I find a realtor if I am behind on payments in Azusa?
- Who can help me sell my Azusa house before foreclosure?
- How do I find a pre-foreclosure realtor in Azusa?
- How do I find a foreclosure alternative agent in Azusa?
- What happens after a notice of default if I want to hire an Azusa realtor?
- How do I find a loss mitigation realtor in Azusa?
- How do I find a mortgage hardship realtor in Azusa?
- How do I find a lender-approved short sale agent in Azusa?
- Who is a pre-foreclosure realtor in Azusa?
- Who can negotiate a short sale with my mortgage company in Azusa?
- Can a realtor help me avoid foreclosure in Azusa?
- Can an Azusa realtor help if I am facing foreclosure?
- Who can help me sell a distressed house in Azusa?
- Do I need a special realtor to sell a short sale house in Azusa?
- Can a regular real estate agent list a short sale in Azusa?
- What does a short sale listing agent do for an Azusa homeowner?
- How do I find an underwater property realtor near me in Azusa?
- How do I find a pre-foreclosure realtor near me in Azusa?
- Who is an Azusa realtor who helps with short sales?
- How can a short sale listing agent in Azusa help?
- Do I need an Azusa short sale listing agent?
The CFPB describes a short sale as selling your home for less than you owe, if your lender or servicer agrees. That path is selling a house for less than the mortgage balance in Azusa, sometimes called a mortgage short sale in Azusa. You can also book a seller consultation, review Azusa home values, or read the Azusa real estate agent note. If the house is part of an estate, see the Azusa probate note. This note is general information, not legal, tax or credit advice, and it does not promise approval or debt forgiveness.
To talk through next steps for the property, start an Azusa short sale consultation.
Current Azusa market snapshot
Azusa home values at a glance
As of .
$702,000
Median sold price in Azusa, last 90 days
76 closed sales in the last 90 days · median 31 days on market · $477 per sq ft · 85 active listings in Azusa.
Source: CRMLS, as of . Deemed reliable, not guaranteed.
Qualifying in Azusa
Do You Qualify for a Short Sale in Azusa, and What Goes in a Hardship Letter?
Each lender sets its own short sale criteria, but an Azusa homeowner usually needs a home worth less than the loan balance and a documented hardship, such as job loss, illness, divorce or a death in the family. A hardship letter explains what happened, briefly and truthfully, alongside the financial documents the servicer requests.
Servicers commonly ask for income records, bank statements, tax returns and a listing agreement. Ask your servicer for its exact short sale package, and ask a HUD-approved housing counselor to review it. No one can promise that an Azusa hardship package will be accepted.
Azusa short sale timeline
How Long Does a Short Sale Take in Azusa?
There is no set timeline. An Azusa short sale needs ordinary marketing time, shown in the live Azusa days-on-market figure on this page, plus the lender's review after an offer arrives. A second loan, an investor or a mortgage insurer can each add review time, and no one can promise a lender decision date.
Buyers on an Azusa short sale often wait for the lender's answer before their loan and inspection timelines start in earnest. Ask the servicer for written status updates and keep copies of everything you send.
Lender approval in Azusa
Will the Lender Approve an Azusa Short Sale?
Approval is never certain. The lender or servicer decides whether to accept an Azusa short sale offer based on its own guidelines, the home's value, the borrower's finances and any investor or insurer rules. Only the lender's written approval letter, with its stated terms, makes the short sale final. No agent can promise approval or forgiveness.
The CFPB says to get any agreement in writing and to understand its terms before going through with a short sale. Read the approval letter's deficiency and cost terms with a California attorney before signing.
Azusa foreclosure alternatives
Short Sale, Foreclosure, Deed in Lieu or Loan Modification: Which Fits an Azusa Homeowner?
They are different tools. A loan modification changes the loan terms so you can keep the home. A short sale sells an Azusa house for less than owed, with lender approval. A deed in lieu voluntarily hands the home to the lender. Foreclosure is the lender's forced sale. A HUD-approved counselor can compare the options.
See the CFPB pages on a loan modification and a deed in lieu of foreclosure, which suggest asking for a written deficiency waiver and note that a deed in lieu may still create a tax liability. The CFPB's avoid foreclosure page lists other options. Which path fits an Azusa household is a question for a housing counselor and a California attorney.
Second loans on an Azusa house
What If You Have a Second Mortgage or HELOC on an Azusa House?
Every lien holder must agree before an Azusa short sale can close, including a second mortgage or HELOC lender. Each lender reviews the offer and may ask for its own payment or terms. California Code of Civil Procedure section 580e limits deficiency claims by each consenting holder of a qualifying deed of trust. Ask an attorney.
Liens such as tax liens or judgments also need to be released or paid at closing. A title report early in an Azusa short sale shows every lien that must be resolved. See CCP section 580e.
Credit and an Azusa short sale
How Does an Azusa Short Sale Affect Your Credit?
A short sale is reported to the credit bureaus, and the effect depends on your full credit history and on how the lender reports the account. Missed payments before an Azusa short sale also appear on your report. No one can promise a specific score result. A HUD-approved housing counselor can review your credit situation with you.
Ask the servicer, in writing, how it will report the account after an Azusa short sale closes. A HUD-approved housing counselor is free or low cost. Sidney does not give credit advice.
Deficiency and CCP 580e in Azusa
Can the Lender Come After You for the Balance After an Azusa Short Sale?
For many Azusa homeowners, no. California Code of Civil Procedure section 580e generally bars a deficiency after a short sale of a one-to-four-unit dwelling when the note is secured solely by a deed of trust and the holder consents in writing. Exceptions include entity borrowers, fraud and waste. Have an attorney review the approval letter.
Section 580e also says the holder cannot require the borrower to pay additional compensation as a condition of consent, and a waiver of these protections is void. It does not apply when the borrower is a corporation, limited liability company or limited partnership, or in cases of fraud or waste. Whether it covers this Azusa loan is a question for a California attorney. Sidney does not promise debt forgiveness.
1099-C and an Azusa short sale
Do You Owe Taxes on Forgiven Debt After an Azusa Short Sale?
Possibly. IRS Topic 431 says canceled debt is generally taxable, and the lender may send Form 1099-C after an Azusa short sale. The qualified principal residence exclusion covers debt discharged before January 1, 2026, or under a written agreement made before then. Other exclusions, such as insolvency, may apply. Ask a CPA before you sign.
See IRS Topic 431 and Publication 4681. California tax treatment can differ from federal treatment. A CPA or tax attorney should review the approval letter for this Azusa sale. Sidney is not a tax adviser.
Living in an Azusa house during a sale
Can You Stay in Your Azusa House During a Short Sale?
Usually yes, until closing, if you keep the home available for showings and follow the purchase contract. Mortgage payments, property taxes and insurance remain your obligations unless the servicer agrees otherwise in writing, and a foreclosure already under way may not stop on its own. Ask how a pending Azusa short sale affects any sale date.
Moving dates are negotiated in the purchase contract and must fit the lender's approved closing date. Keep the Azusa house insured and maintained while it is listed.
Commission on an Azusa short sale
Who Pays the Real Estate Commission on an Azusa Short Sale?
On a short sale, the commission is usually paid from the sale proceeds, so the lender's approval letter sets how much it will allow. The seller and broker agree on the rate in the listing agreement. An Azusa seller should read the approval letter's settlement terms with an attorney before signing.
The amount or rate of real estate commissions is not fixed by law. They are set by each broker individually and may be negotiable between the seller and broker. Confirm any Azusa agent's license on the DRE public lookup.
Azusa rentals and investment homes
Can You Short Sell an Azusa Rental or Investment Property?
Yes, lenders review rental short sales too, but the rules differ. Section 580e covers dwellings of one to four units, yet it excludes borrowers that are corporations, LLCs or limited partnerships. Tenants' rights continue, and tax treatment of canceled debt on an Azusa rental can differ from a home. Get attorney and CPA advice.
Local rent and eviction rules for an Azusa rental come from the City of Azusa as well as state law. A California landlord-tenant attorney confirms which apply before any notice goes to a tenant.
Notice of default in Azusa
What Happens After a Notice of Default on an Azusa House?
A notice of default starts California's nonjudicial foreclosure clock. Under Civil Code section 2924, at least three months must pass before a notice of sale, and the sale date cannot be earlier than three months and 20 days after the default is recorded. A short sale on an Azusa house may still be possible during that window.
A California timeline that often comes up after a notice of default on an Azusa house.
3 months + 20 days
The waiting period Civil Code section 2924 describes before a trustee's sale, in most cases
See the CFPB's notice of default page and Civil Code section 2924. Call the servicer as soon as a notice arrives, and contact a HUD-approved housing counselor or a California attorney about this Azusa property.
Options for an Azusa homeowner
Behind on Payments or Underwater on an Azusa House: What Are Your Options?
An Azusa homeowner who is behind or owes more than the home is worth can ask the servicer about loss mitigation, such as forbearance, a repayment plan, a loan modification, a short sale or a deed in lieu. A free HUD-approved housing counselor can help compare them. If there is equity, a regular sale may work instead.
The CFPB's avoid foreclosure page walks through these options. A HUD-approved counselor is not a substitute for a California attorney or a CPA. If you have equity, review Azusa home values first.
Azusa short sale pricing
How Much Can an Azusa Short Sale House Sell For?
A lender usually wants an Azusa short sale priced near market value, so it reviews comparable Azusa sales and often orders its own valuation. The live median and recent Azusa sales on this page show the local price level. The lender, not the seller or agent, decides whether an offer is high enough.
The live Azusa snapshots are a community backdrop when enough complete sales support them, not a value for your address. A personal review is an informal market analysis, not an appraisal.
Azusa short sale figures at today's prices
What the Azusa market means for a short sale
As of .
$702,000
Median sold price in Azusa, last 90 days
- Median days on market
- 31 days in Azusa, last 90 days. Lender review time comes on top of marketing time.
- Closed sales, last 90 days
- 76 in Azusa. Lenders often compare a short-sale offer with recent nearby sales like these.
- Active listings now
- 85 in Azusa, the competition a short-sale listing would face.
- Transfer tax at the median price
- About $772 at $1.10 per $1,000 on a $702,000 Azusa sale. Escrow calculates the actual amount.
Source: CRMLS, as of . Deemed reliable, not guaranteed. Not tax or legal advice.
What Azusa homes have sold for
Recently sold homes in Azusa
As of .
 SoldMLS# WS26034330
644 E Lee Place
644 E Lee Place
Listing Agent: Sherry Hung, Listing Office: Real Brokerage Technologies
 SoldMLS# WS26157620
758 E Matchwood
758 E Matchwood
Listing Agent: MAY CHEN, Listing Office: CALLAWAY REALTY, INC.
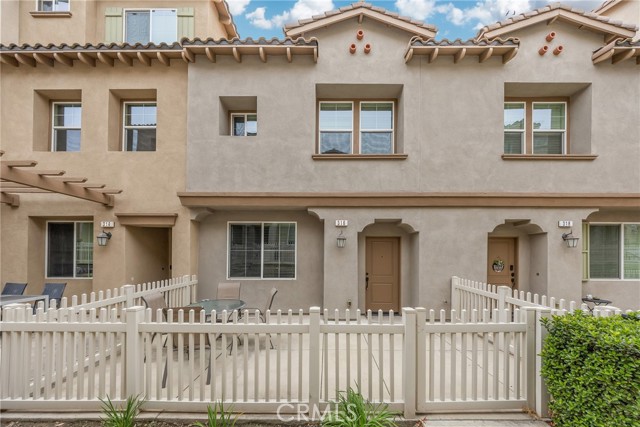 SoldMLS# OC26182468
316 N Calvados
316 N Calvados
Listing Agent: Grace Gui, Listing Office: Keller Williams Realty Irvine
Source: CRMLS, as of . Deemed reliable, not guaranteed.
Sold data from CRMLS. Sidney Manzo may not have represented either party.
Transfer taxes on an Azusa short sale
Do Transfer Taxes Apply on an Azusa Short Sale?
Los Angeles County collects a documentary transfer tax of $1.10 per $1,000 on an Azusa sale. Azusa is not on the Registrar-Recorder's list of cities with an additional city rate, and Measure ULA does not apply. On a short sale, the lender's approval letter sets which seller costs it will allow from the proceeds.
Transfer-tax figures that often come up on an Azusa sale.
$1.10 / $1,000
Los Angeles County documentary transfer tax
On a typical Azusa deed, Los Angeles County collects a documentary transfer tax of $0.55 per $500, which is $1.10 per $1,000 of value exclusive of remaining liens. The Los Angeles County Registrar-Recorder lists additional city rates only for Culver City, Los Angeles, Pomona, Redondo Beach and Santa Monica; Azusa is not on that list. Measure ULA does not apply in Azusa. If Azusa has adopted a conforming city documentary transfer tax under California Revenue and Taxation Code section 11911, that city share is credited within the countywide $1.10 per $1,000, not added on top. Ask your escrow officer or a real estate attorney who pays the tax under your contract. Sidney does not pay transfer taxes and does not give tax advice.
Local rules for an Azusa short sale
What Local Azusa Rules Can Affect a Short Sale?
Azusa is its own incorporated city in Los Angeles County, so building permits, planning and historic-preservation questions for an Azusa parcel go to the City of Azusa. Check parcel-specific rules with the City before the short sale listing goes live. Sidney does not determine historic status and does not pull permits.
Planning and building questions for an Azusa parcel belong with the City of Azusa. The City publishes adopted specific plans, including Rosedale, the Monrovia Nursery Specific Plan, Mountain Cove, and the TOD Specific Plan; confirm whether any of those plans apply to your property. This guide does not treat a citywide point-of-sale inspection as a confirmed City of Azusa requirement from the official sources reviewed on November 16, 2026. Ask the City or a California attorney what applies. Sidney does not pull or pay for permits and does not give legal advice.
Permit and building records: City of Azusa website. To talk through how those Azusa rules affect a listing, you can book a seller consultation.
Finding an Azusa short sale real estate agent
How Do You Find the Best Short Sale Real Estate Agent in Azusa?
There is no official ranking of short sale real estate agents in Azusa. Look for a California-licensed listing agent who can explain lender review, hardship packages and local comparable sales. Interview Sidney Manzo, CA DRE #01108914, about pricing and timing. He cannot promise approval. A first talk is a consultation, not a listing appointment.
When choosing an Azusa short sale realtor, short sale real estate agent or short sale listing agent, ask how they would price the home using comparable Azusa sales, assemble a hardship package, present offers to the lender or servicer, and keep you informed during review. People also search for a short sale specialist in Azusa or a short sale agent in Azusa; those phrases describe a California-licensed listing agent, not a separate license or a claim about any one person. No agent can promise that a lender will approve a sale, forgive a balance or produce a particular credit outcome. The amount or rate of real estate commissions is not fixed by law. They are set by each broker individually and may be negotiable between the seller and broker.
Book a seller consultation. Confirm any license on the DRE public lookup.
An Azusa realtor who helps with short sales
Who Is An Azusa Realtor Who Helps With Short Sales?
People looking for an Azusa realtor who helps with short sales want a listing agent for a home that may sell for less than the loan. Sidney Manzo, CA DRE #01108914, represents Azusa sellers and can discuss pricing. The lender decides whether to approve a sale. He is not an attorney or housing counselor.
The same is true if you searched for a realtor because of an Azusa underwater mortgage, owe more than the house is worth, are behind on payments, or are considering selling a house before foreclosure in Azusa. Sidney works with. He is not a foreclosure consultant and cannot delay or stop a foreclosure. Book a seller consultation to talk about pricing and a possible listing. A HUD-approved housing counselor or a California attorney can compare legal and financial options.
Short sale listing agent work in Azusa
What Does a Short Sale Listing Agent Do for an Azusa Homeowner?
A short sale listing agent for an Azusa homeowner lists the house, helps assemble a hardship package and presents offers to the lender. Only a written approval letter makes the sale final. The agent cannot promise approval, forgiveness or a credit outcome. Ask a HUD-approved counselor or an attorney about legal and financial questions.
California does not require a separate short-sale license. A regular, California-licensed real estate agent can list an Azusa home as a short sale once you have agreed to listing terms. A "lender-approved short sale agent" search describes the lender's role in approving the sale; it is not a separate state credential. A lender-approved short sale in Azusa is a sale the lender has agreed to in writing, not a promised result. People looking for short sale assistance in Azusa are usually trying to hire a listing agent for the property. The listing agent handles marketing and the file; the lender or servicer decides. See the CFPB's What is a short sale? page.
Short sale realtor near me in Azusa
How Do You Find a Short Sale Realtor Near Me in Azusa?
To find a short sale realtor near me in Azusa, check the DRE license lookup, interview listing agents about short-sale work and ask a HUD-approved counselor for a referral. Sidney Manzo, CA DRE #01108914, works with Azusa sellers. A first talk covers pricing. It is not legal advice, and no agent can promise approval.
The same starting steps apply if you are looking for a short sale real estate agent near me, a short sale listing agent near me, a pre-foreclosure realtor near me, or a realtor specializing in short sales near me in Azusa. Book a seller consultation, or start with the Azusa real estate agent note, the DRE public license lookup, and HUD's counselor tool.
Contact · Azusa short sale
How Do You Contact Someone About an Azusa Short Sale?
Use the form on this page or book a seller consultation to talk with Sidney Manzo, CA DRE #01108914, about pricing and listing an Azusa home as a short sale. A first talk covers comparable Azusa sales and timing. It is not legal, tax or credit advice, and not a promise that a lender will agree.
Book a seller consultation, call (626) 296-2900, or review Azusa home values first.
About Sidney · Azusa short sale
About Sidney Manzo and Azusa Short Sales
Sidney Manzo, CA DRE #01108914, represents sellers, including people selling a home in Azusa. His professional background includes more than 155 closed sales on his agent profile, and the RE/MAX Hall of Fame Award. He lives in Pasadena and is a member of the Pasadena Foothills Association of REALTORS®. He is not an attorney, tax adviser or housing counselor. A first conversation is a consultation, not a listing appointment.
Source: California Regional Multiple Listing Service (CRMLS). Last updated Nov 17, 2026, 2:21 AM PT.
Based on information from California Regional Multiple Listing Service, Inc. as of Nov 17, 2026, 2:21 AM PT and /or other sources. All data, including all measurements and calculations of area, is obtained from various sources and has not been, and will not be, verified by broker or MLS. All information should be independently reviewed and verified for accuracy. Properties may or may not be listed by the office/agent presenting the information.
IDX information is provided exclusively for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Sold data from CRMLS. Sidney Manzo may not have represented either party.
Information deemed reliable but not guaranteed.
Sources and Professional References
Short sale definitions and options: the Consumer Financial Protection Bureau pages What is a short sale?, deed in lieu of foreclosure, loan modification, notice of default and avoid foreclosure, and HUD's Find a housing counselor tool. California law: Code of Civil Procedure section 580e and Civil Code section 2924. Federal tax: IRS Topic 431 and Publication 4681. License lookup: the DRE public license lookup. City sources: the City of Azusa website, the City's planning page. Transfer tax: the Los Angeles County Registrar-Recorder's documentary transfer tax page and California Revenue and Taxation Code section 11911. Sources reviewed November 16, 2026.